Market Data
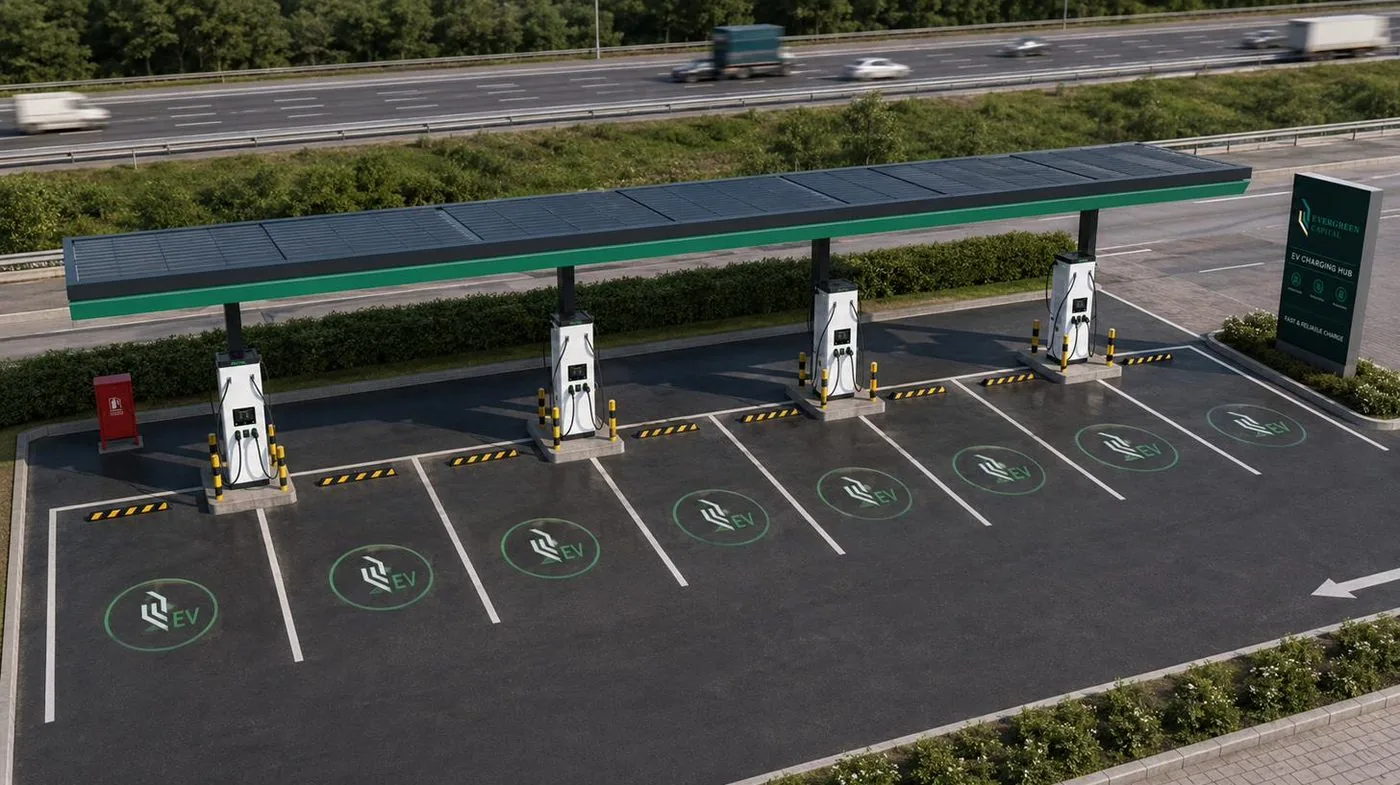
Thailand's electric vehicle transition is no longer a projection — it is happening on the road, in registration data, and in the queues that form at busy charging stations. But the charging network has not kept pace with vehicle adoption, and the numbers show a widening gap that well-located charging stations will be needed to close.
Thailand's accumulated battery-EV registrations have grown almost fivefold since 2021, reaching approximately 339,116 vehicles, according to figures compiled by the Electric Vehicle Association of Thailand (EVAT). Momentum has continued: industry tracking put new EV registrations at roughly 66,000 units in just the first seven months of 2025 — nearly matching the entire 2024 total of about 67,000 — with passenger BEV sales up 61% year-on-year in the first half of 2025.
Between June 2024 and December 2025, Thailand's BEV passenger-car stock increased by 127.7%. Over the same period, public charging connectors grew by only around 20%. Demand is compounding several times faster than supply — and every month that continues, the utilisation case for existing and new stations strengthens.
Thailand ended 2024 with 11,467 public charging points across roughly 3,720 station locations, split almost evenly between AC and DC chargers, according to the Roland Berger EV Charging Index 2025. Set against the vehicle fleet, that works out to roughly 24 EVs per public connector by end-2025. China — the world's most developed EV market — operates at around 6 vehicles per connector.
Public charging remains heavily concentrated in Bangkok and other major urban areas, with rural corridors underserved. Network operators are responding — PTT's EV Station PluZ, the market leader with close to 30% share of public charging, has announced plans to grow to 7,000 charge points by 2030 — but the geographic spread of demand is widening faster than any single operator's footprint.
The national target calls for 12,000 DC fast chargers by 2030, alongside highway coverage at intervals of no more than 100 km on major routes. Today's DC network is well below half that figure. Closing the gap is a multi-year build-out — and a commercial opportunity for the site owners and investors who position early, in locations where drivers actually need to charge.
A structural shortage of charging relative to vehicles supports utilisation at well-chosen sites. It does not make every site viable: traffic, dwell time, grid capacity, and tariff eligibility still determine the economics of an individual location. That is what a professional site assessment establishes before capital is committed.
Sources: Electric Vehicle Association of Thailand (EVAT); Roland Berger, EV Charging Index 2025 — Thailand (rolandberger.com); IEA, Global EV Outlook 2026 (iea.org); Market Research Thailand, H1-2025 EV registration tracking; National EV Policy Committee targets. Figures as reported at the dates cited; registration data updates monthly.
← Insights
Our no-obligation site assessment reviews location, traffic, parking, electrical capacity, and commercial potential to determine the right project configuration.
Request a Free Site Assessment